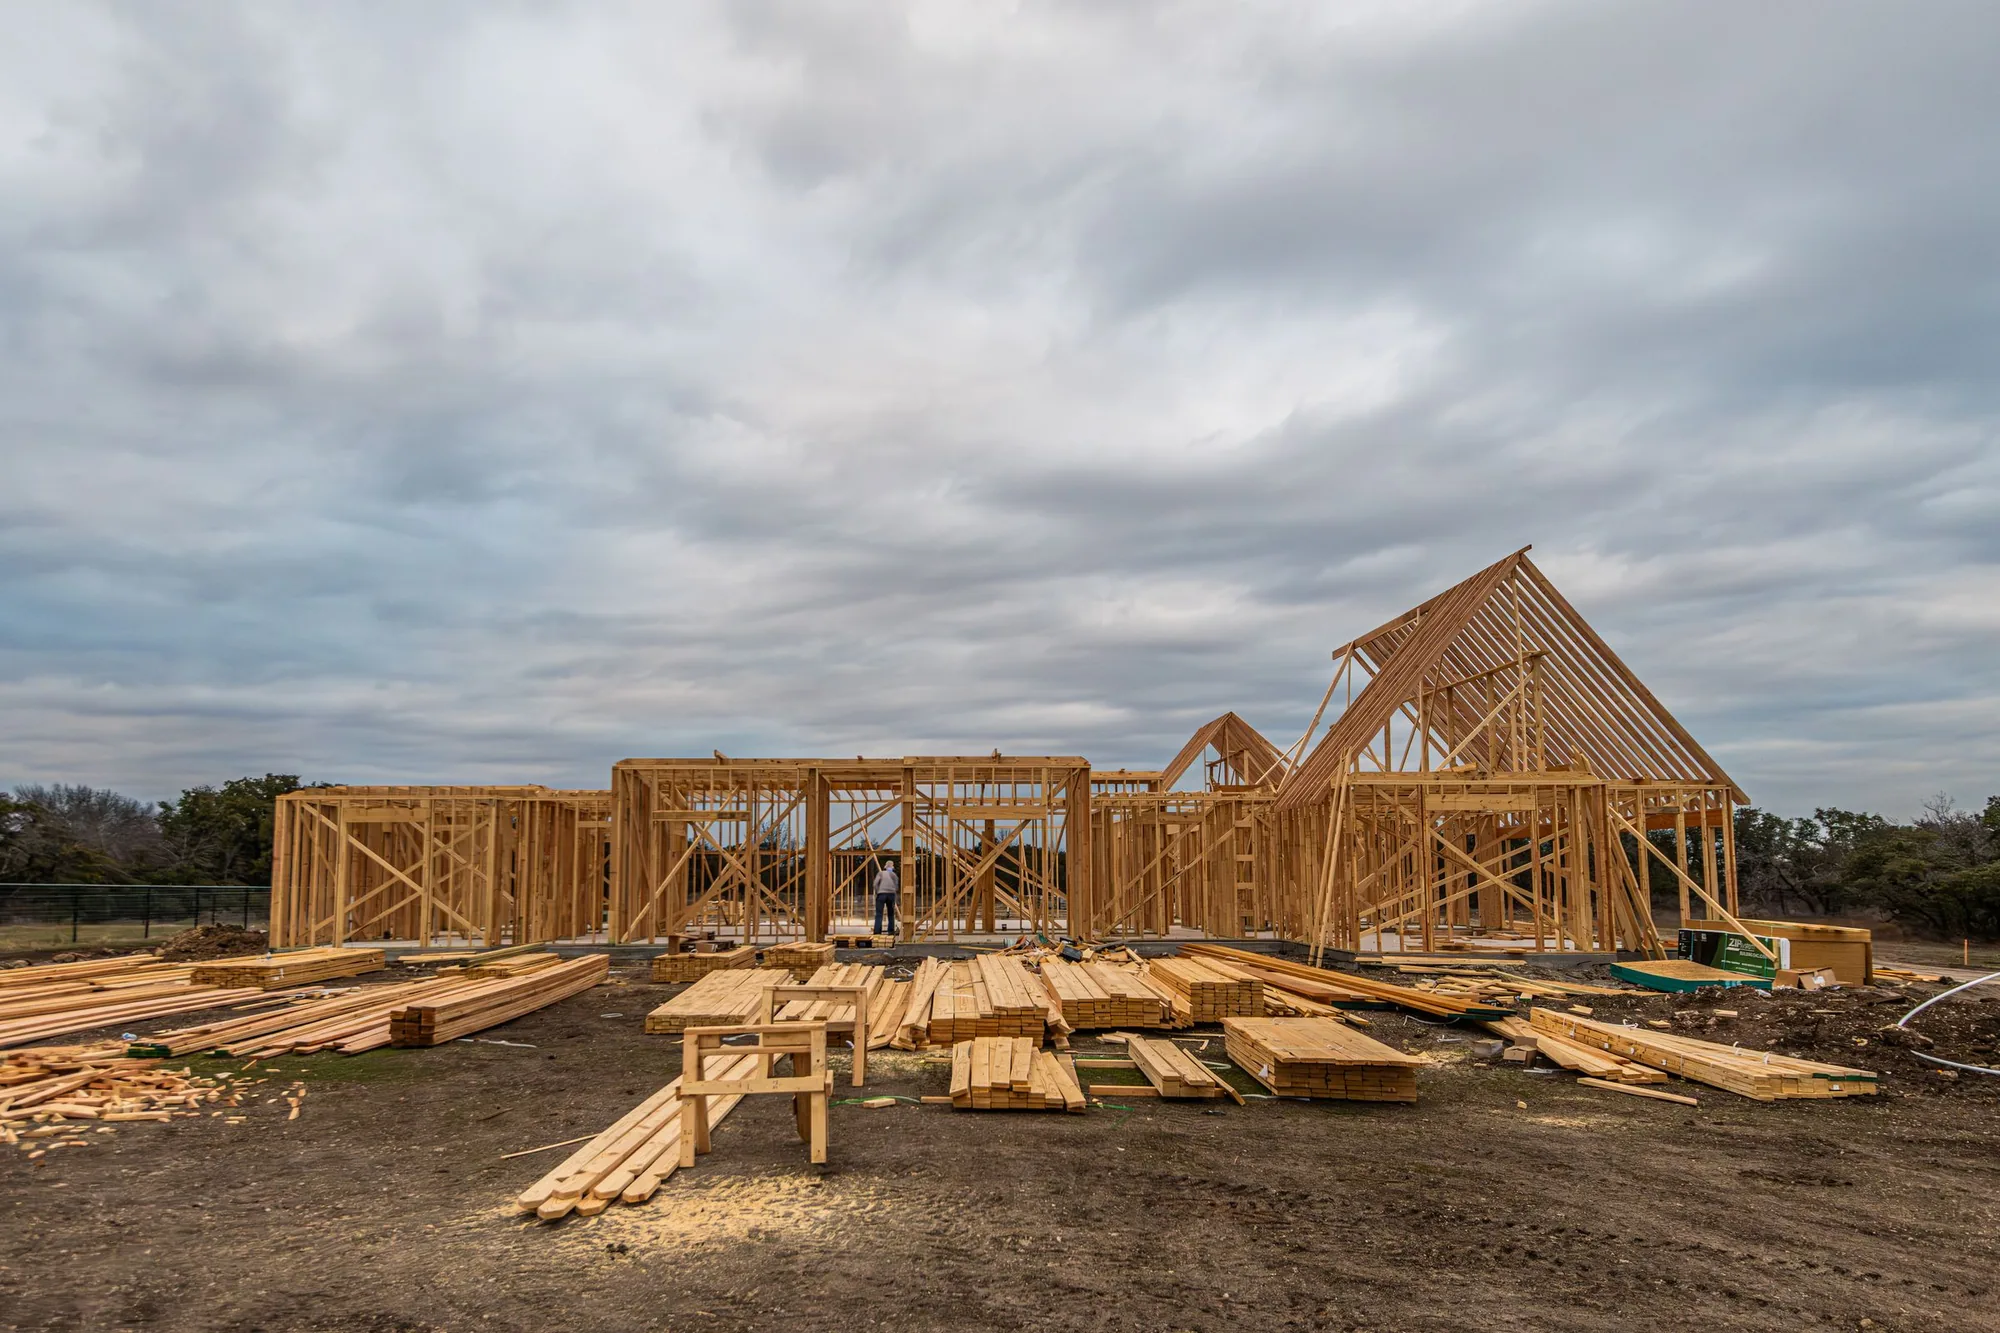
What is a construction loan?
A construction loan pays for building a new home. The money is usually paid out in draws as the work moves along, and the loan may turn into a regular mortgage when the home is done. Terms depend on the lender, the builder and the project.
Who looks at a construction loan
- Buyers building a new home
- Buyers working with a licensed builder
Where a construction loan can help
- Pays for the build
- May turn into a regular mortgage at the end
The steps, in order
A first conversation, then a review of your goals and finances, then comparing loans. After that come a secure application, your documents, underwriting, and final approval and closing. No approval is implied before underwriting.
- 1.A first conversation
- 2.A review of your goals and finances
- 3.Comparing loans
- 4.A secure application
- 5.Your documents
- 6.Underwriting
- 7.Final approval and closing
What to weigh with a construction loan
- More steps than buying a finished home
- Needs plans, permits and an approved builder
- The draw schedule has to be managed
What a lender reviews for a construction loan
- Credit and income review
- An approved builder and plans
- The project budget and appraisal
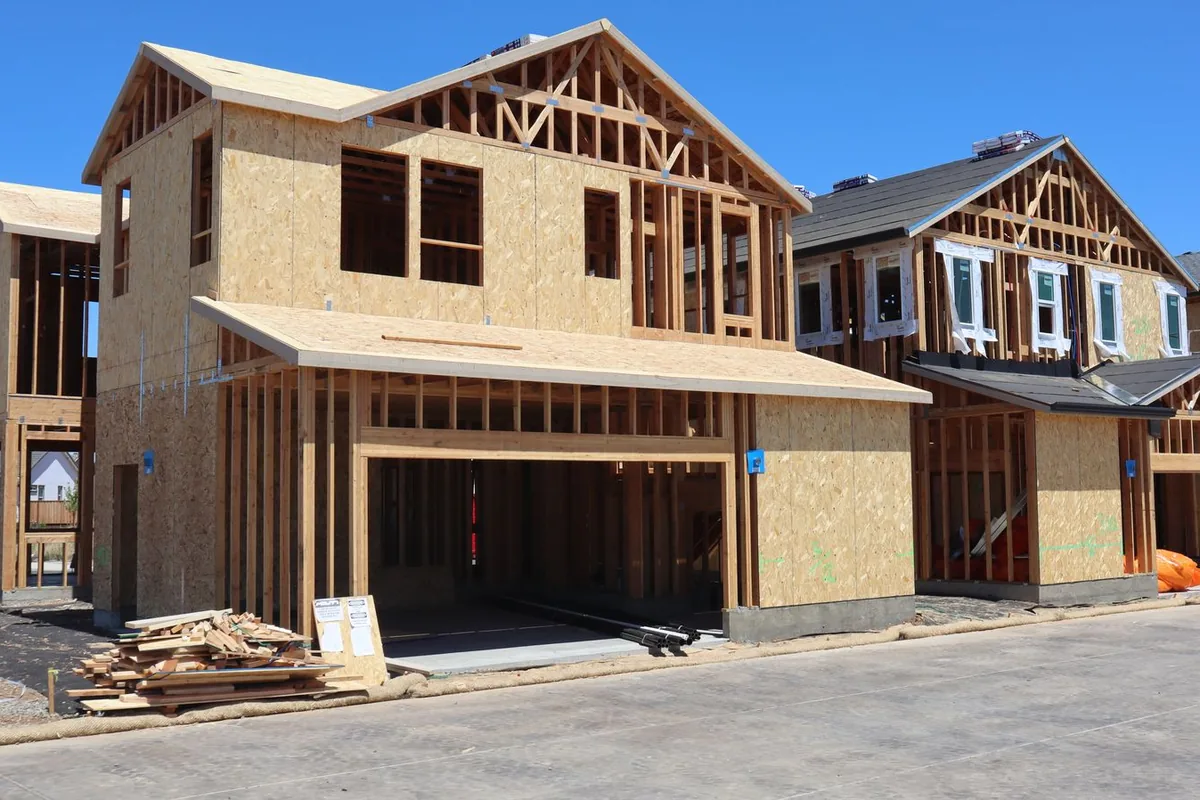
Property rules for a construction loan
- • Approved plans and permits
- • An appraisal of the finished home's value
Documents for a construction loan
- Plans and specifications
- The builder contract
- Proof of income and assets
The down payment on a construction loan
Mortgage insurance on a construction loan
Questions to ask Bert about a construction loan
- Does my situation fit this kind of loan?
- What documents will I need?
- What costs should I plan for besides the down payment?
- How do draws work?
- Does this turn into a regular mortgage?
Talk it through with Bert
Program availability and eligibility vary. Ask Bert whether this loan fits your situation.
Schedule a CallImportant
This is educational information, not a commitment to lend or a guarantee of eligibility. Eligibility, pricing, rates, and terms depend on the borrower and transaction. A licensed mortgage professional must review your complete scenario.